
Buying Dubai property from Europe: plan the cross-border details
Prepare for currency transfers, remote representation, document checks and tax advice when buying and managing a Dubai property from Europe.
Published · Updated · 3 min read
Buying Dubai property while living in Europe adds practical questions to the ordinary purchase process: how funds will move, who can sign, which documents are acceptable and how the property will be managed when you are elsewhere. Address these early so they do not become last-minute obstacles to completion.
The official UAE ownership guidance explains the framework for foreign purchasers. Eligibility still depends on the precise property and registered interest. Our foreign-buyer guide covers those transaction fundamentals.
Plan the money transfer around the contract
Build the purchase budget in the currency you will actually pay, then translate it into your savings or income currency. Include conversion spreads, transfer charges and the possibility that the exchange rate moves before the next instalment.
Ask your sending bank what source-of-funds evidence it requires and how long a substantial transfer may take. Keep the sale documents and account details consistent. Independently confirm any change of beneficiary through a known contact channel, rather than relying on a forwarded message.
Decide whether you will attend or appoint a representative
Confirm the signing and registration arrangements with the receiving authority and service providers. If a power of attorney is needed, establish its scope, execution, authentication and translation requirements before preparing it in your home country.
Ask who will inspect the property, witness agreed repairs, attend handover and collect documents. Authority to sign a purchase should not be assumed to cover every later task. Keep copies of the accepted instrument and all documents signed on your behalf.
Obtain finance before relying on it
A lender will assess your income, liabilities, residency status and the property under its own underwriting policy and the UAE mortgage framework. Overseas income can involve additional documentary and currency questions. Obtain a case-specific assessment and understand the conditions that remain before final approval.
Compare financing with a cash purchase using the cash or mortgage guide. Include the possibility that valuation or transfer timing increases the cash you need at completion.
Keep tax and residence questions separate
Europe is not one tax jurisdiction. Ask a qualified adviser in the country relevant to your tax residence about rental income, capital gains, reporting, inheritance and any applicable treaty treatment. Obtain advice on UAE obligations appropriate to your ownership and activity as well.
A property purchase or UAE residence visa does not by itself settle where you are tax resident. Avoid building the investment case around a broad “tax-free” claim without examining your circumstances.
Put remote ownership in writing
Agree the manager’s authority, fees, repair-approval limit, reporting frequency and handling of tenant deposits. Clarify who pays utilities during vacancies and how emergency work is authorised. Retain access to contracts, statements and invoices.
Review the full ownership budget with those arrangements included. The aim is an asset you can understand and supervise from abroad, with enough cash and reliable representation to manage an ordinary problem without an urgent flight.
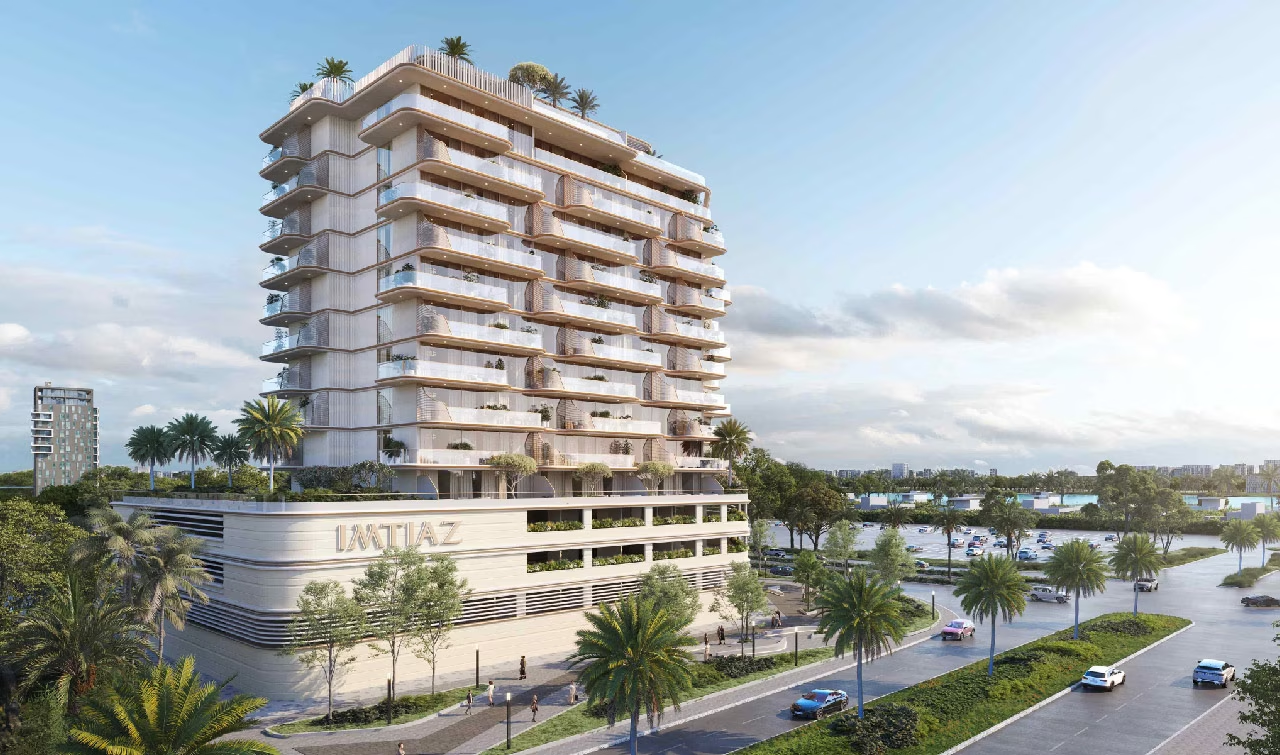
Sources checked 2 October 2026. Images rechecked 5 October 2026. Captions distinguish developer renderings, community photographs and original Imperial Alfa guide graphics.